If you bought or renewed a variable-rate mortgage in Edmonton over the last few years, 2026 is the year a lot of households are asking the same two questions: should we lock a fixed term now, and what will it actually cost to get there? The honest answer is not a screenshot of today’s posted rate. It is penalty math, remaining term, and whether a blend-and-extend at your current lender beats a full switch across a broker panel.
Jason Scott is an independent mortgage broker with TMG The Mortgage Group in Edmonton. He has more than 15 years in the YEG market and shops 20+ lenders rather than defending one bank’s product sheet. This guide is educational. It is not a rate lock, a penalty quote, or a promise that a switch will save you money. Every closed mortgage has lender-specific break rules. Run the numbers on your statement before you move.
Serving homeowners in Windermere, Terwillegar, Riverbend, Glenora, Oliver, and Strathcona, plus Sherwood Park, St. Albert, Leduc, Spruce Grove, and Stony Plain. Start at edmontonmortgagebroker.com or call 780-721-4879.
Why Edmonton files are asking about a variable-to-fixed switch in 2026
Variable payments moved a lot through the last rate cycle. Some Edmonton households kept the variable because they expected cuts. Others want payment certainty before a job change, a parental leave, or a move from a west-end townhouse into a Riverbend or Windermere detached. A slower listing market in parts of the city also means more owners are staying put and re-working the mortgage they already have instead of selling.
A switch is not the same as a renewal. Renewal is the cleanest moment to change lenders with little or no break penalty. Mid-term, you are asking to break a closed contract. That is where IRD and three-month interest stop being jargon and start being a four- or five-figure line item.
Jason’s job at TMG is to put those numbers beside the new payment, the new term, and the features you actually use (prepayments, portability, a future HELOC on a collateral charge) so you can see whether the move is worth it.
The two penalty formulas in plain language
Canadian closed mortgages usually charge the greater of two calculations when you break early. You need both, even if you only remember one from a blog.
- Three-month interest. Take your current balance, apply the interest rate on the mortgage (or the lender’s stated penalty rate), and charge roughly three months of that interest. It is the simpler formula. On many variable products, this is the penalty you actually pay.
- Interest rate differential (IRD). This asks: if the lender re-lends your remaining balance today at a current rate for a similar remaining term, how much interest do they lose versus keeping you at your existing rate? That gap, over the months left on your term, is the IRD. When rates have fallen since you locked a fixed rate, IRD can be far larger than three months of interest.
Two traps show up constantly on Edmonton statements. First, some lenders calculate IRD off a posted rate instead of the discounted rate you actually pay, which inflates the penalty. Second, people compare a new five-year payment to their current payment and ignore the break cost sitting in front of that savings. A cheaper payment that takes seven years to recoup a penalty is not a win if you might move again in three.
Variable files: why three-month interest is usually the starting math
Most variable-rate mortgages in Canada use a three-month interest penalty (or a close cousin) when you break a closed variable. That is why a variable-to-fixed switch can look cheaper to execute than breaking a deep-discount fixed from two years ago. It is not free. On a $450,000 balance, three months of interest is still real money. It is usually knowable in one sitting with your current statement and a lender penalty worksheet.
Before you assume “variable equals cheap to break,” confirm three things with the actual lender:
- Is the product a closed variable, an open variable, or a convertible structure with its own conversion window?
- Is the penalty strictly three-month interest, or the greater of three-month interest and an IRD-style calculation?
- Are there discharge, reinvestment, or collateral-charge costs on top of the penalty?
Convertible products are a different article. If your term already lets you convert to fixed on a set formula, use that path first. Do not pay a full break penalty to do what the contract already allows.
Fixed files: IRD can dwarf three months of interest
If you are already on a fixed rate and shopping a new fixed, or you blended into a fixed earlier, IRD is the number that surprises people. A household in Glenora or Oliver who locked when rates were higher may have a modest IRD. A household who locked a low five-year fixed and now wants out with years left can see an IRD that makes the switch pointless until renewal.
Ask for the penalty in writing. Then ask which rate the lender used in the IRD (posted vs discounted, and which comparison term). Jason will translate that letter into a recoup timeline: months of payment difference versus the cash cost to break. If the recoup sits past the date you might sell a Terwillegar townhouse or port into a Spruce Grove move-up, the math usually says wait.
Blend-and-extend vs a full switch to a new TMG lender
Blend-and-extend means you stay with the current lender. They blend your remaining rate with a current rate, then extend you into a new term. The appeal is obvious: you often avoid (or sharply reduce) the break penalty. The cost is equally obvious: you do not shop the rest of the TMG panel, and the blended rate plus the new term length may be worse than paying a known three-month penalty and moving.
A full switch (or a refinance, if you are increasing the amount) means Jason compares 20+ lenders for rate, term, prepayment room, portability, and how they treat a later equity take-out. You pay whatever break penalty applies, plus legal and possible appraisal costs, then start clean with the new lender.
Blend-and-extend tends to win when IRD is large, remaining term is long, and you like the current lender’s servicing. A full switch tends to win when the penalty is three-month interest, remaining term is short, or you need a structure your bank will not offer – for example a readvanceable setup, a different amortization, or a lender that will consider a future purchase in Sherwood Park without trapping you in a hard-to-discharge collateral charge.
This is not a slogan. It is a side-by-side: penalty + legal + new payment + features you will use. If a bank “blend” quote arrives with no IRD worksheet attached, treat it as incomplete.
Switch vs refinance: insured, uninsured, and when equity changes the file
Language gets sloppy here. In Canadian practice:
- A switch usually moves the remaining balance to a new lender without taking extra cash out. At renewal this is often the lowest-friction path. Mid-term, the break penalty still applies unless the contract says otherwise.
- A refinance changes the amount, amortization, or both – debt consolidation, a renovation, or pulling equity. Qualifying is a new underwrite. The B20 stress test applies at the qualifying rate, typically the greater of your new contract rate plus two percentage points or the OSFI minimum qualifying rate (5.25% as of the current guideline). Credit unions and some alternative lenders may use different internal rules; federally regulated lenders follow B-20.
If the original purchase was high-ratio and CMHC-insured (or insured by another default insurer), remaining insurance can often transfer on a straight switch of the insured balance. If you refinance above that balance, you may be looking at a new uninsured file once you have 20% equity, or a new insurance conversation if you do not. Do not assume insurance “just carries” when you are increasing the loan.
Uninsured files (typically 20% or more equity) still qualify under B20 at most banks. A refinance that pushes past 80% loan-to-value is a different product conversation. Jason will say so early rather than let a Windermere appraisal and a title search run for a structure that cannot close.
A Canadian HELOC (home equity line of credit), often as part of a readvanceable / collateral-charge setup, can be the right tool when you want revolving access after the switch. It is not automatic, it still qualifies, and some collateral charges make a later lender switch harder. Ask about the charge type before you sign a “convenient” all-in-one.
Neighbourhood-level examples across Edmonton and the region
The formula is national. The decision is local because sale timelines, renovation plans, and job patterns differ by pocket.
- Windermere / Terwillegar / Riverbend. Many 2018-2023 purchases sit on variables or short remaining terms. If you are two years from a planned move-up, paying IRD to lock five more years can be the wrong clock. If the penalty is three-month interest and you want payment certainty through a parental leave, a switch can still make sense.
- Glenora / Oliver / Strathcona. Older housing stock and renovation plans show up here. A refinance that funds a kitchen and also resets the rate is a different file than a pure rate switch. Get the penalty and the project budget on the same page.
- Sherwood Park and St. Albert. A lot of switch requests are really “we might buy a larger place in 18 months.” Portability and penalty recoup matter more than a 0.10% rate gap.
- Leduc, Spruce Grove, and Stony Plain. Commuter households and energy-sector income variability mean payment shock is the real stress, not the headline rate. Map the new payment at a stressed qualifying rate, not only at contract rate.
Bring your current mortgage statement, remaining term, prepayment privileges already used this year, and a one-line goal (lower payment, certainty, cash-out, or prepare to port). That is enough for a first pass.
How Jason Scott shops 20+ lenders at TMG The Mortgage Group
A single bank will quote its own blend and its own penalty. An independent broker process puts that quote next to other lenders’ switch and refinance pricing, including how they calculate IRD and whether they will wait for your renewal instead. TMG’s panel is the point: you are not stuck defending the institution that already holds the charge.
Typical sequence:
- Pull the current statement and request a written penalty from the existing lender.
- Classify the file: closed variable, closed fixed, convertible, insured vs uninsured, conventional vs collateral charge.
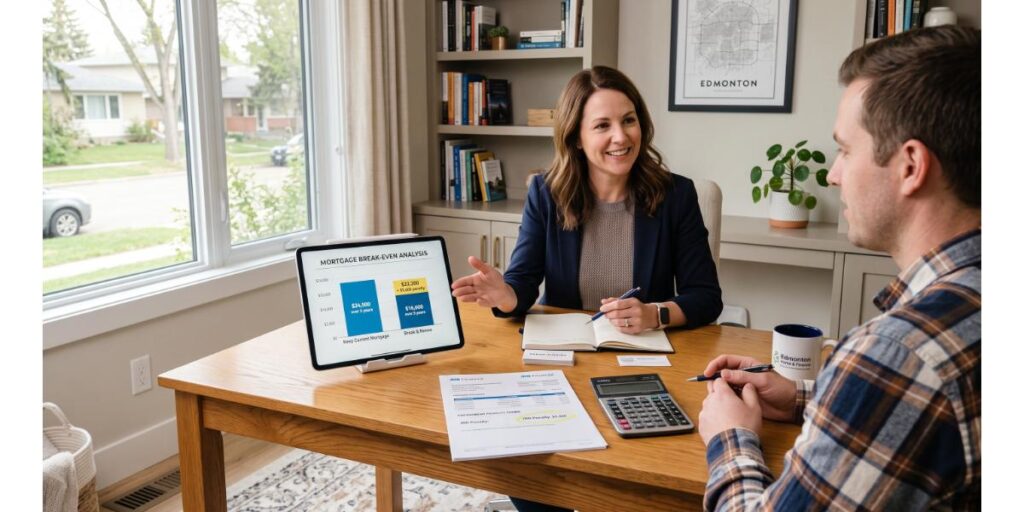
- Build two live options: blend-and-extend (stay) vs break-and-switch or refinance (move), with recoup months attached.
- Stress the new payment under B20 qualifying rules so you know approval is real, not a teaser payment.
- Only then talk term length, prepayments, and whether a HELOC belongs in the structure.
Office: 10525 170 Street NW Unit 107, Edmonton. Consultations start at edmontonmortgagebroker.com or 780-721-4879.
Frequently asked questions
Is breaking a variable always cheaper than breaking a fixed?
Often the variable penalty is three-month interest and the fixed penalty is a larger IRD – but not always. Read the charge on your specific product. Open and convertible structures are different again.
Will I fail the B20 stress test if I switch?
A straight switch of the same balance at renewal is usually the easiest qualify. A mid-term refinance or a higher amount is a new underwrite. Federally regulated lenders qualify you at the greater of contract rate plus 2% or the OSFI minimum qualifying rate (currently 5.25%). Income, debts, and property type still have to clear.
Can I switch without a full refinance if I am not taking cash out?
Often yes, especially near renewal. Mid-term you still face the break penalty. Jason will tell you if the cheaper path is waiting 4-8 months versus paying to move now.
Does CMHC insurance transfer on a switch?
Remaining default insurance on an insured balance can often transfer with a straight switch. Increasing the loan, changing occupancy, or mixing in extra debt can change that. Confirm on your file; do not assume.
Should I wait for my renewal date instead?
If IRD is large and you have no cash-out or product need, waiting is frequently the winning move. If the penalty is modest and payment certainty or a better structure matters this year, run the recoup math rather than waiting by default.
How do I start with Jason Scott?
Send your current statement and remaining term through edmontonmortgagebroker.com or call 780-721-4879. Ask for a penalty-and-switch comparison, not a single rate quote.
Jason Scott – TMG The Mortgage Group – Edmonton Mortgage Broker – 10525 170 Street NW Unit 107, Edmonton, AB T5P 4W2 – https://edmontonmortgagebroker.com/ – 780-721-4879
Educational information for Alberta homeowners. Not a rate guarantee, penalty quote, or commitment to lend. All mortgages are subject to lender approval, qualifying rules including Guideline B-20 where applicable, and the terms of your existing contract. Jason Scott is a mortgage broker with TMG The Mortgage Group, Edmonton. Licensing: RECA (verify on RECA ProCheck). Rates and insurer rules change.